

The Big Picture
August was a very slow month in Squamish. Buyer activity weakened, homes took longer to sell, and sellers were accepting noticeably more below their original asking prices.
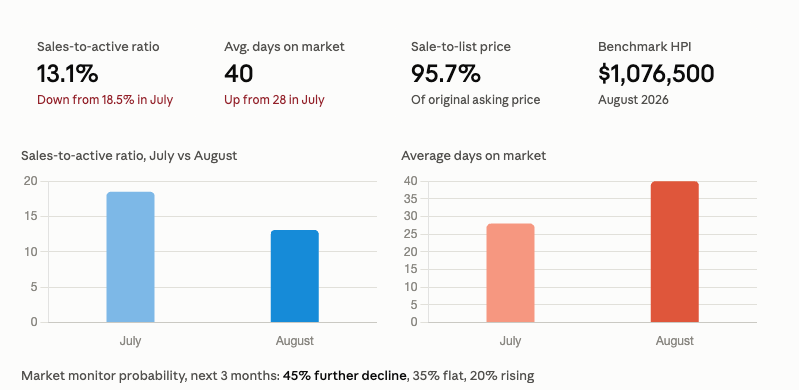
That softness is showing up clearly in the numbers: the sales-to-active listings ratio fell to 13.1%, average days on market rose to 40, and homes sold at an average of 95.7% of original asking price.
The toughest areas right now are one-bedroom apartments, many townhomes around $900,000 to $1 million, and detached homes without a suite or another strong value proposition.
There is one encouraging shift: newer listings are starting to come on at more realistic prices. With interest rates no longer looking certain to fall, some sellers appear more willing to meet the market now rather than wait for spring.
August Market Scorecard
Buyer Activity is Weakening — August activity slowed materially, with the sales-to-active listings ratio falling to 13.1%.
Inventory is Elevated — Buyers have substantial choice, although inventory normally begins its seasonal decline after the September listing bump.
Pricing is Softening — Benchmark HPI was $1,076,500 and the average sale-to-original-list ratio fell to 95.7%.
Negotiating Power favours Buyers — Longer marketing times and deeper discounts from asking price are giving buyers meaningful negotiating leverage.
Mortgage Rates are a Headwind — The prospect of rates remaining elevated or moving higher is weighing on confidence and purchasing power.
Overall Outlook is Cautious — Near-term downside risk remains elevated even though Squamish's long-term fundamentals are still attractive.
Where the Market Is Moving
There isn't one Squamish market right now.
Price point and functionality matter more than broad property type. Homes offering clear value, income potential or a compelling location are holding up better than comparable homes without those advantages.
Detached Homes in the Entry & Mid Market are Strong — still active when the home offers strong value or income potential.
Detached Homes in the Upper Mid Market are Balanced — selective, especially for homes without a suite.
Luxury Detached Homes are Slower — small buyer pool and very price-sensitive.
Affordable Townhomes are Strong — still moving when priced competitively.
Mid-Priced Townhomes are Balanced — one of the more difficult segments, particularly around $900,000 to $1 million.
Luxury Townhomes are Slower — competing directly with detached and duplex alternatives.
Entry-Level Apartments are Balanced to Strong — one-bedroom units are currently very difficult for sellers.
Mid-Range Apartments are Balanced — plenty of choice and stronger negotiating leverage.
Premium Apartments are Slower — very price-sensitive with a limited buyer pool.
What the Numbers Are Telling Us
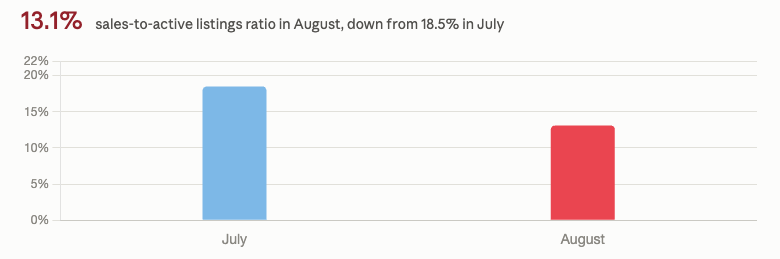
Buyer Demand Slowed Sharply — the sales-to-active listings ratio fell from 18.5% in July to 13.1% in August, confirming what we felt on the ground: buyers were far less active.
The Asking-Price Gap Has Widened — homes sold at an average of 95.7% of original asking price, while average days on market rose to 40 from 28 in July.
Affordability Remains the Largest Challenge — affordability remains a major constraint, especially with borrowing costs no longer clearly trending lower.
Opportunity — buyers have more negotiating power than they have had in some time.
From Simon's Desk
The simplest way I can describe the market right now is this: buyers are patient, and sellers need to be realistic.
Well-priced homes can still sell, but the days of testing the market with an ambitious price are becoming harder to justify.
For sellers, pricing correctly from the beginning matters more than ever. For buyers, this is a market where patience and negotiation can create real opportunity.
Looking Ahead
The near-term outlook remains cautious.
September often brings a short-lived increase in listings before inventory declines through fall and winter, so falling listing counts alone should not be read as a stronger market.
What matters most is whether buyer activity improves and whether sellers continue to adjust prices toward where transactions are actually happening.
Team Hudson's Market Insight
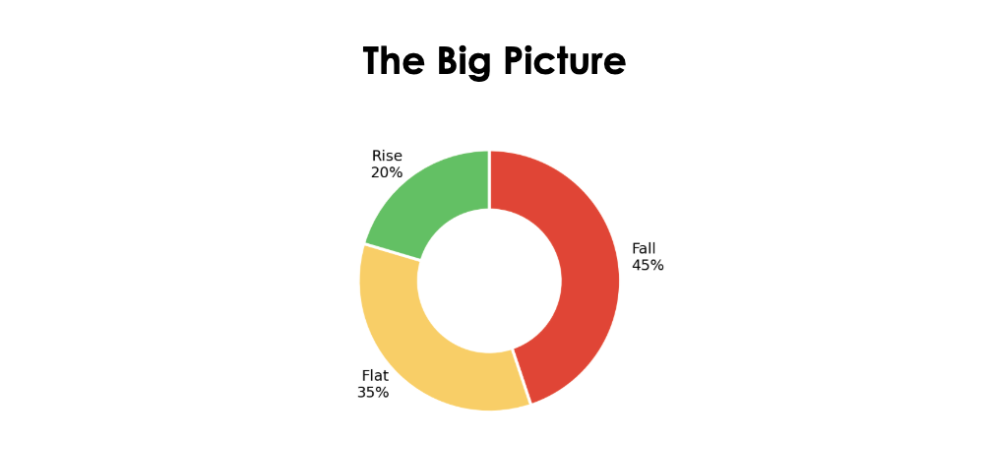
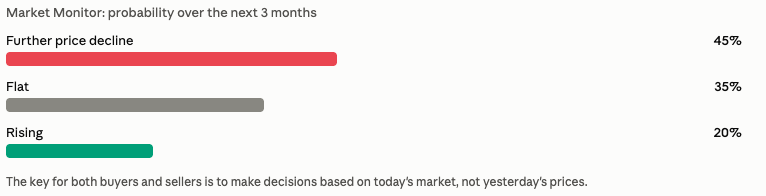
August clearly favoured buyers. Our Market Monitor currently shows a 45% probability of further price decline over the next three months, compared with 35% flat and 20% rising. The key for both buyers and sellers is to make decisions based on today's market, not yesterday's prices.
 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.